A budget tells you how this month went. A net worth tracker tells you how your whole financial life is going. One is the weather, the other is the climate.
It’s also the most encouraging number you can watch, once you get past the first look. Plenty of people start with a negative net worth: student loans, a car loan, a credit card. That’s normal. The point isn’t where you start. It’s watching the line move up, month after month, as debts shrink and savings grow.
Here’s how to work out your net worth, what to include, and how to track it without it taking over your Sunday.
The net worth formula
Net worth = what you own (assets) minus what you owe (liabilities).
That’s all. The work is in listing everything properly.
Assets
- Cash: checking, savings, the emergency fund, the cash jar
- Retirement accounts and investments, at today’s value
- Your home, at a realistic market value (not what you hope it’s worth)
- Vehicles, at resale value
- Anything else you could sell for real money
Liabilities
- Mortgage balance
- Car loans
- Student loans
- Credit card balances (the full balance, even if you pay it off monthly)
- Personal loans, buy now pay later, money owed to family
Leave out furniture, clothes and electronics. They’re worth far less than you paid, and counting them just makes the number feel better than it is.
A quick example
Say you have $2,800 in checking and savings, $14,500 in a retirement account and a car worth $9,000. That’s $26,300 in assets. On the other side: $11,200 left on the car loan, $18,600 in student loans and $1,400 on a credit card. That’s $31,200 in liabilities.
Net worth: minus $4,900.
Not a fun number. But six months later, with the card cleared, $2,400 more in savings and the loans paid down a bit, it might be minus $900. A year after that, positive. Watching that happen is what keeps people going.
How often to update a net worth tracker
Monthly is the sweet spot. Weekly is too noisy; investment balances bounce around and you’ll drive yourself mad. Yearly is too slow to notice progress.
Pick a fixed day, like the first of the month or the day after payday. Log in to each account, copy the balances, done. Ten minutes, maybe fifteen the first time.
Five tips for tracking net worth
- Be consistent with values. Use the same method each month for your home and car. Don’t bump the house up because a neighbor sold high.
- Watch the trend, not the month. A market dip can knock your number down for a month or two. Look at the 12-month line.
- Track debt and assets separately too. Sometimes net worth stays flat while debt falls and savings fall at the same time. You want to see that.
- Set a goal. “Positive net worth by December” or “+$10,000 this year” gives the number a purpose.
- Don’t compare with friends. Net worth depends on age, location, career and luck. Your only useful comparison is you, last year.
What to do with the number
A net worth figure on its own is just trivia. It earns its place when it changes a decision.
If the line is flat for three months, look at why. Usually it’s one of two things: spending has crept up and savings have quietly stopped, or a debt balance isn’t falling because you’re only paying the minimum. Either is fixable once you can see it.
If the line is rising, check what’s driving it. Paying down a 24% credit card raises net worth by exactly the amount you paid, and it also stops the interest. An investment gain can disappear next month. Progress you made yourself is the kind that sticks.
And when it crosses zero for the first time? Mark it somewhere. Lots of people remember that month for years.
Net worth tracker tools
A simple spreadsheet with one row per month works. But it’s much easier when the tracker sits inside your budget, so balances update as you log transactions and pay debts. Three options on Taskdale do that.
Calm Cash: net worth with a goal line
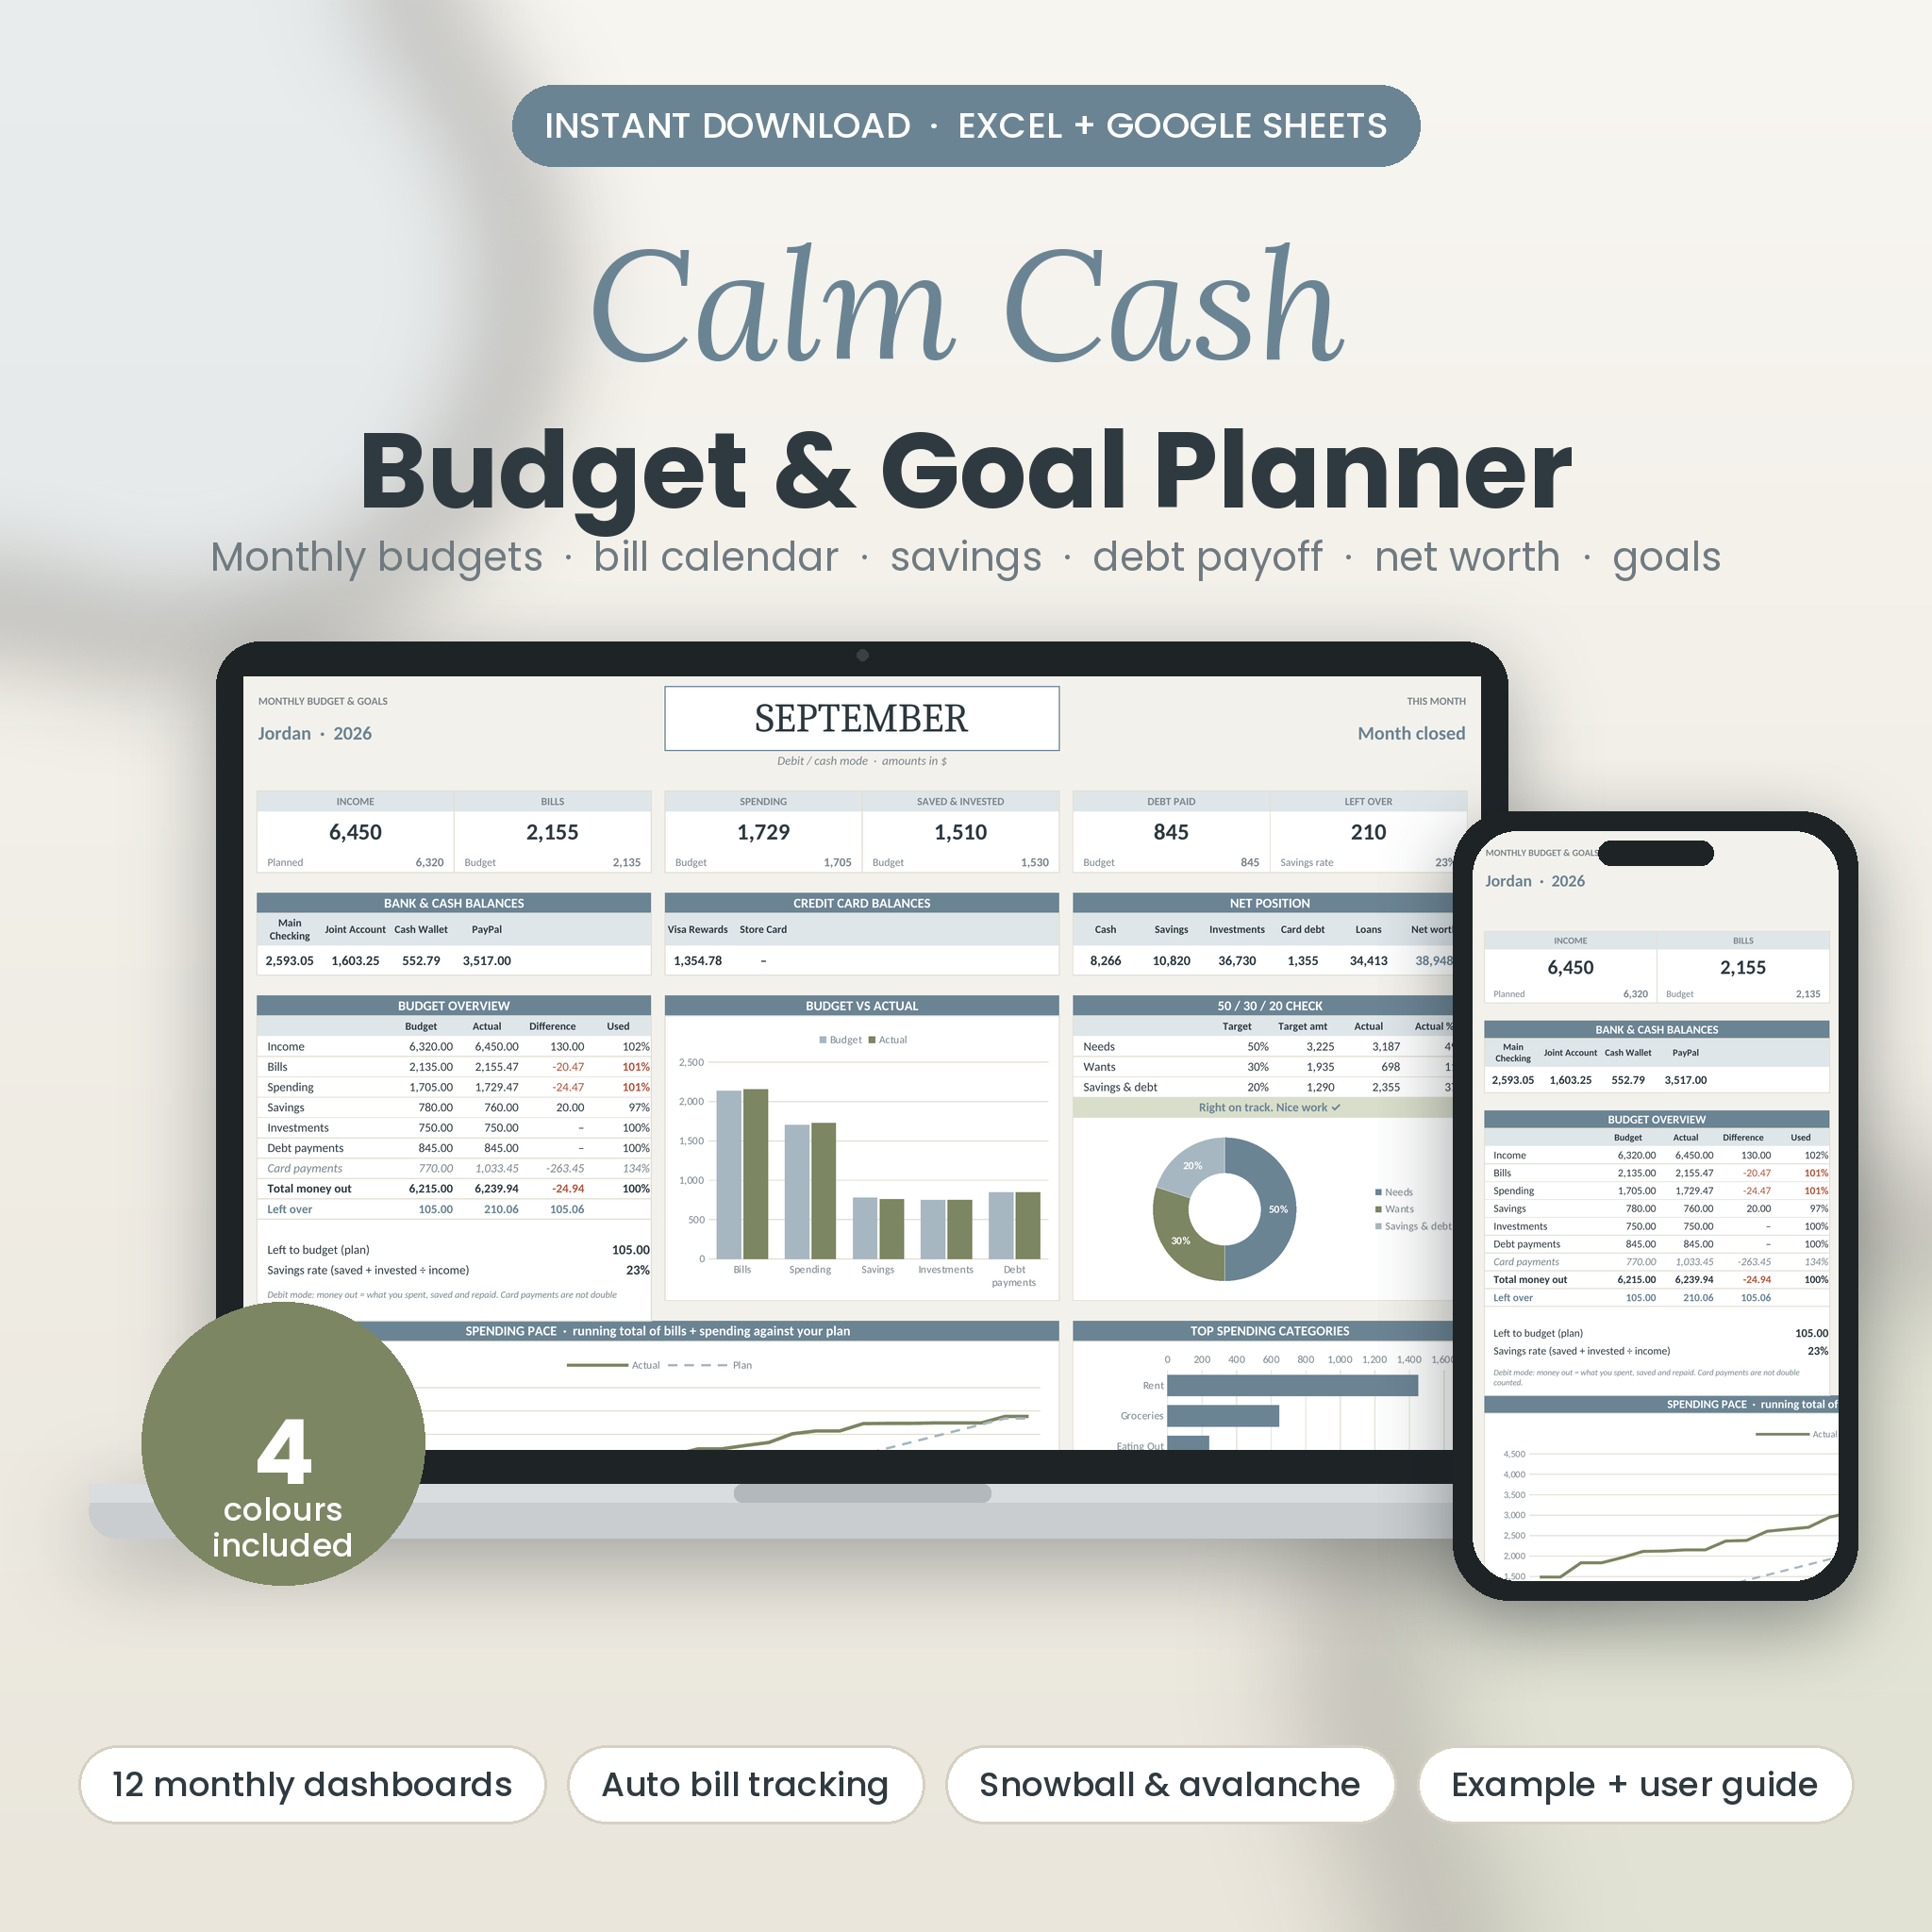
Calm Cash tracks assets minus debts for every month with a trend chart and a goal. Because it’s part of a full annual budget with 23 connected tabs, your account balances, card balances, investments and debt payoff all feed in. The investments tab records contributions, employer match and statement values. It works in Excel 2016 or newer, Excel for Mac 2019 or newer and Google Sheets.
Cedarly Money Hub: an app-style dashboard
Cedarly Money Hub is an offline HTML dashboard rather than a spreadsheet. Its net worth page shows assets minus liabilities by account type, and you save monthly snapshots that build a trend chart. Accounts cover checking, savings, cash, credit cards, loans, investments and assets, with balances calculated from your transactions.
Executive Budget Dashboard: net worth in a detailed budget
The Executive Budget Dashboard tracks net worth monthly and charts it. It’s built to handle real-world quirks: enter a debt as a negative and it still lands correctly in net worth, and transfers between your own accounts stay out of your spending.
For most people tracking net worth alongside a budget for the first time, Calm Cash is the easiest place to start.
Net worth tracker FAQ
Should I include my house in my net worth?
Yes, at a realistic market value, with the mortgage listed as a liability. Some people also track a second figure without the house to see their liquid net worth.
Is a negative net worth bad?
It’s common, especially with student loans or a new car loan. What matters is the direction it’s moving over time.
How often should I update my net worth?
Once a month is enough for most people. It’s frequent enough to see progress and calm enough to ignore short-term market swings.
Do I include retirement accounts?
Yes. They’re assets you own, even if you can’t touch them yet. Use the current balance from your latest statement.